The Landlord Was Selling. The Bank Said "Not Yet." The Argents Bought the House Anyway.
Their landlord was selling and the bank said "not yet." See how the Argents used the Ownable Home Program to buy the home they were renting.
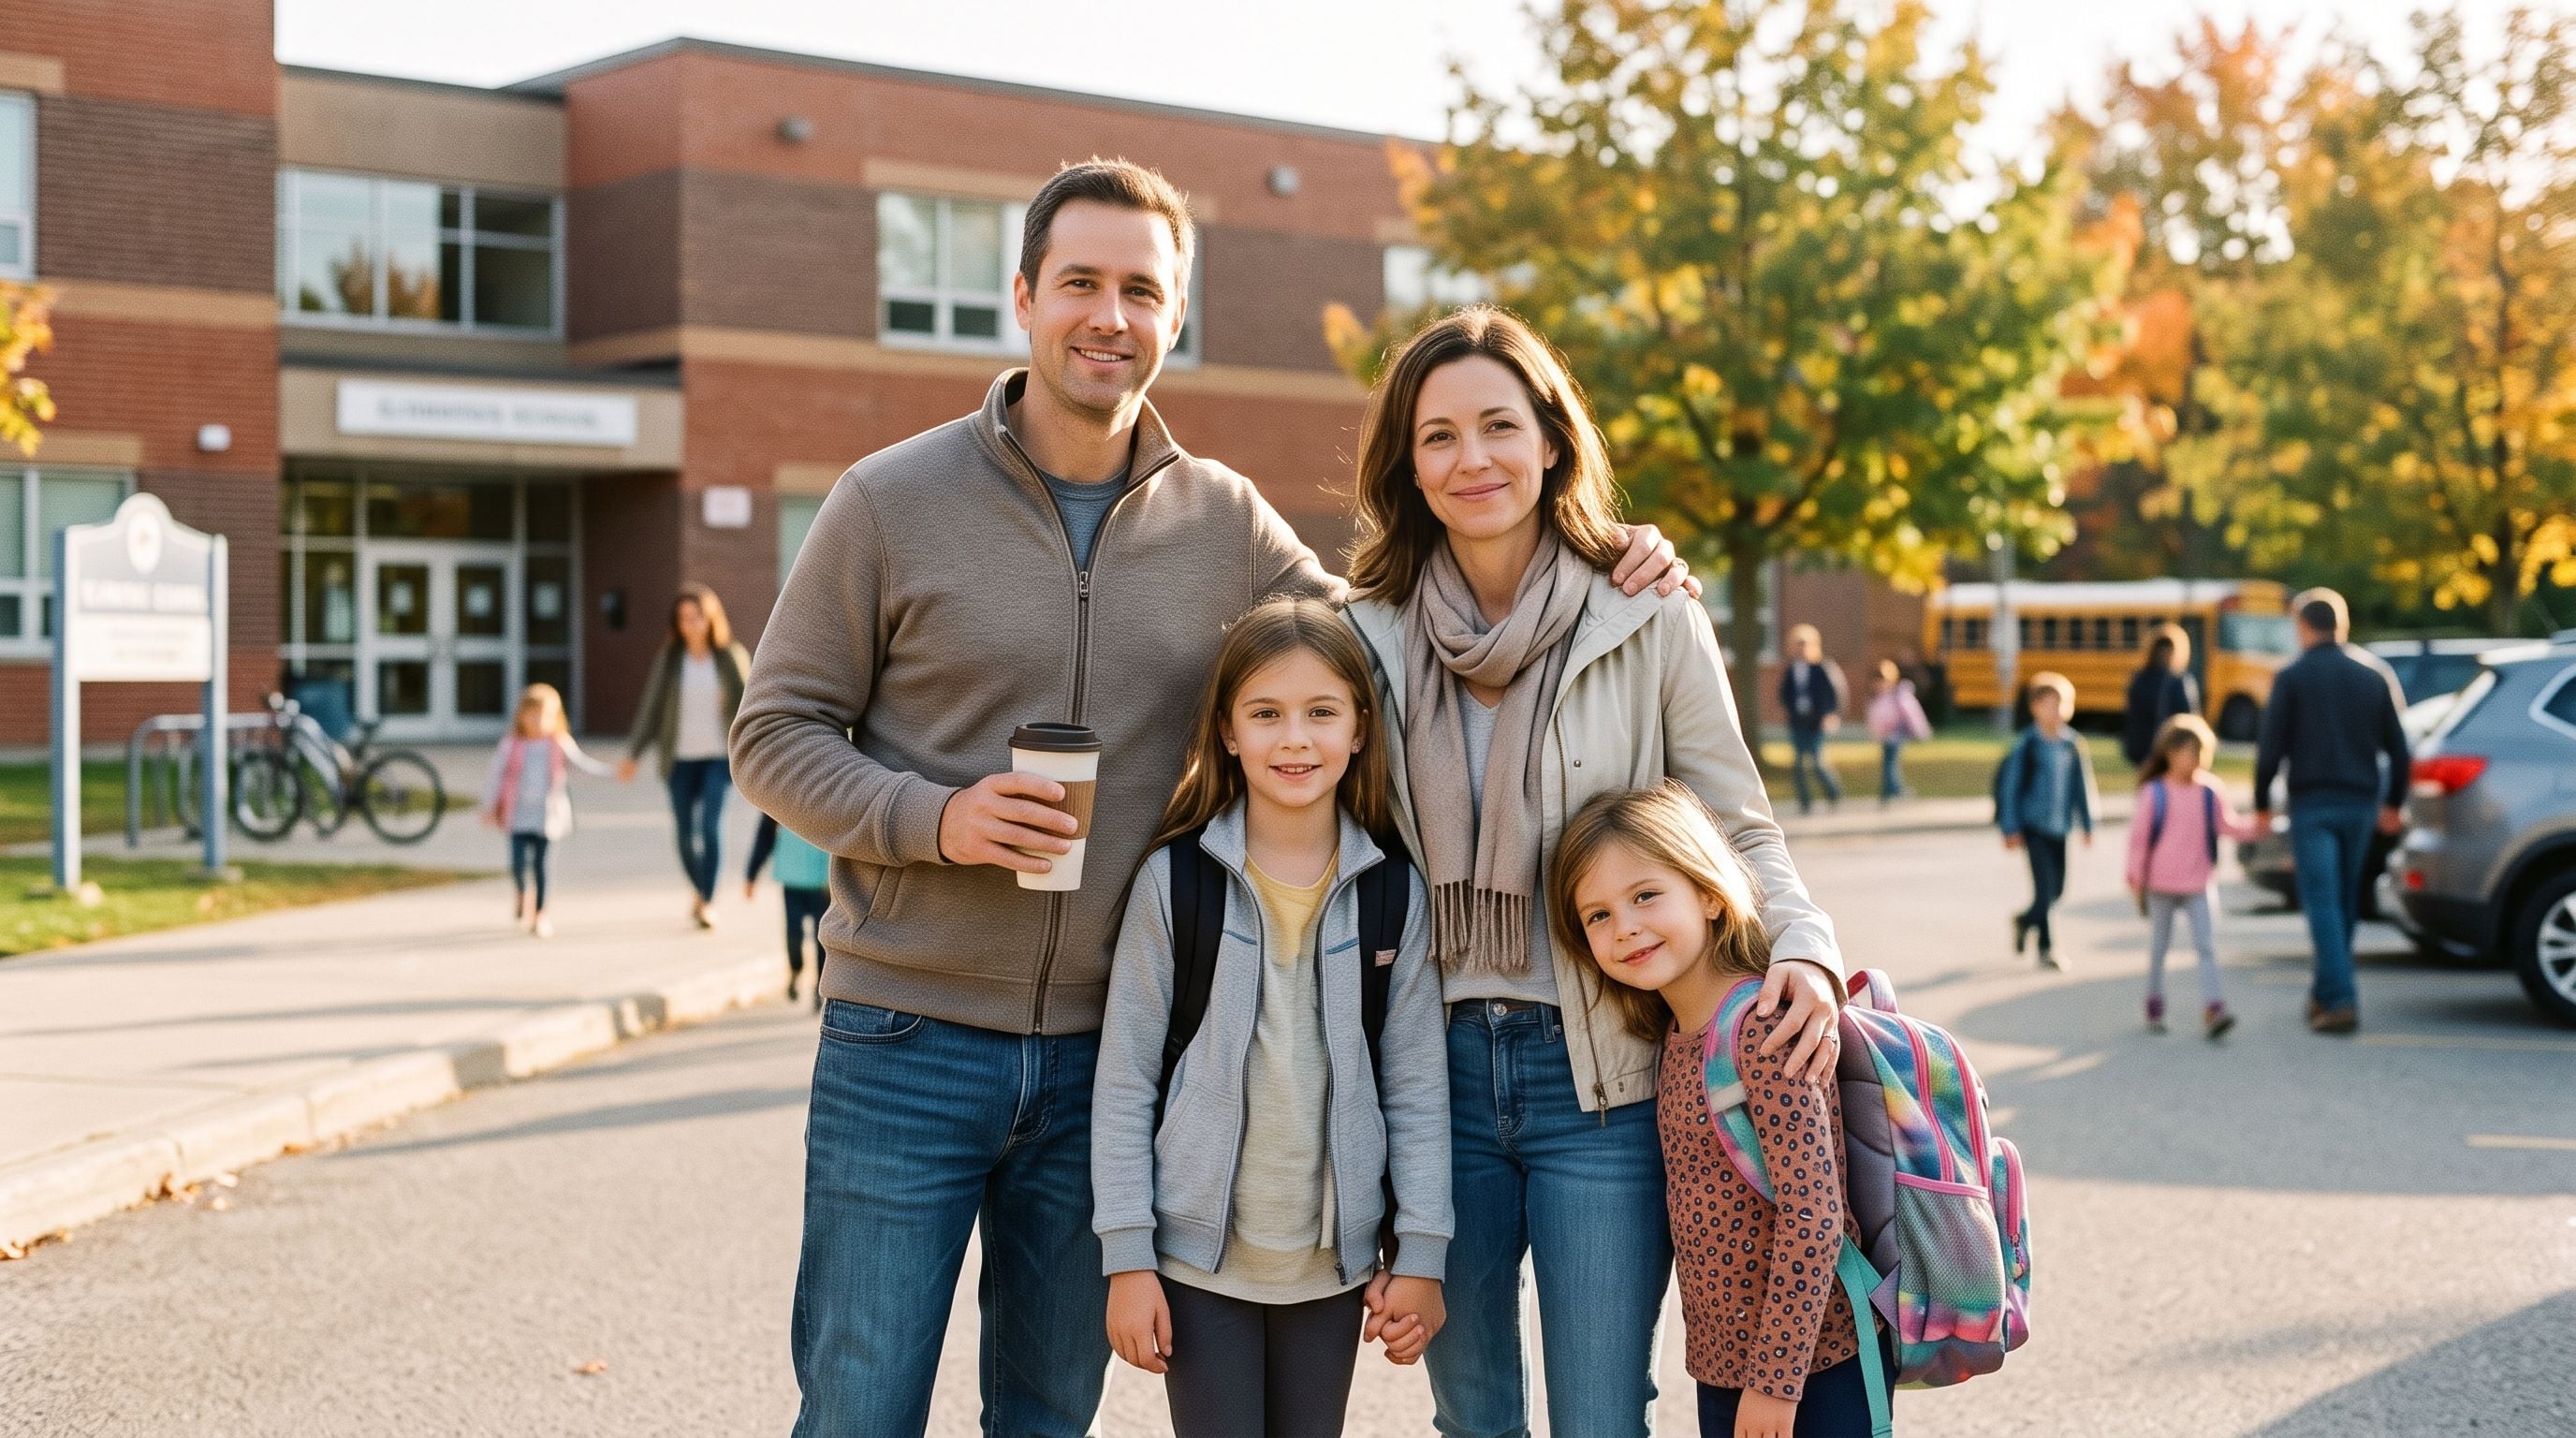
How one Ontario family used the Ownable Home Program to buy the home they were renting — without qualifying for a mortgage first
An Ownable case study
> QUICK ANSWER
>
> Yes, you can buy the home you're renting even if you don't qualify for a mortgage yet. Through the Ownable Home Program, a Financing Partner purchases the home, and the family lives in it as its Future Owner, building an equity stake while they become mortgage-ready. Brandon and Talia Argent used Ownable to buy the house they were renting when their landlord decided to sell. They stayed put, and they now have a written plan to qualify for their own mortgage.
What happens when your landlord sells and you can't get a mortgage?
For most renting families, the answer is simple and painful: you move and face the uncertainty of where you will next live and for how much.
That's where Brandon and Talia Argent were. The kids knew the neighbourhood, the school run was a routine for them and the house felt like home to them in every way except on paper.
Then their landlord told them she was selling.
They wanted to buy it but when they looked into a mortgage, the answer was "not yet." They didn't qualify on their own due to some credit challenges which put them in the realization that the house was going to be put on the market and they would have to consider their next steps.
"We honestly thought it was over," Talia says. "We started looking at rentals. We didn't think there was any other way."
How did the Argents find another option?
A family friend who works as a realtor knew their situation. Instead of helping them find another rental, she asked them a question: had they looked at the Ownable Home Program yet?
They hadn't even heard of it so didn’t consider it as an option. When their realtor gave them an overview, their first reaction was skepticism. Unfortunately, programs that promise homeownership to people who can't get a mortgage have earned it over the years.
What did they do?
They chose to start small and book a free consultation. It couldn’t hurt to see what it was all about even though they felt that it wouldn’t be able to help their situation. They set up the call, did their homework and wrote down every question they had.
The questions they asked:
"We did the call and were relieved that it wasn't a sales pitch," Brandon says. "Neil walked through the program, discussed our situation and started laying out a plan on how it could work for us. Nobody had discussed that with us before."
What is the Ownable Home Program?
Ownable is an equity-building homeownership program and is different from a rent-to-own program. Ownable connects families who aren't mortgage-ready yet with one of its Financing Partners. The Financing Partner buys the home. The family, called the Future Owner, lives in it and builds an equity stake scaled to the down payment they bring in.
The goal is always the same: a conventional mortgage, in the family's own name, when they're ready.
Ownable isn't a way around qualifying. It's a way to stop losing time, and in the Argents' case, a way to stop losing their rental home while they get mortgage-ready.
Did the numbers actually work?
This was the part they were most nervous about and for good reason.
Ownable qualified the Argents first, reviewing their income, credit, savings and debts before discussing the house price and numbers. Once that was done, they did a full budget call to see all the numbers and to figure out if they would work with their monthly budget.
From their research, the monthly payment figure was in line with what a mortgage on the same home would cost them. Ownable calibrates payments to the stress test rate, so what they carry now is in the range a lender will test them against later.
"We weren't stretching to make it work," Talia says. "It looked like a mortgage payment. That's when we knew this was really achievable for us.”
Once they house was found and an accepted offer was placed, they went through a successful home inspection and reviewed the agreements with their lawyer as part of the conditional period. They were given a green light and we firmed up the offer so the house was now sold but to a Financing Partner on their behalf.
What happened next?
The Argents didn't pack a single box. The kids didn't change schools. The question at the dinner table stopped being "where are we going to live?"
Now it's "what do we need to do to be mortgage-ready?"
The fear of being uprooted has been replaced with a project that has a deadline: building credit history, keeping debt in check, and saving for closing costs.
"We're not worried about moving anymore," Brandon says. "We are now focused on the finish line and making this home our own!”
What can other renting families learn from the Argents?
Frequently asked questions
Can I buy the house I'm renting if I don't qualify for a mortgage?
Possibly. Through the Ownable Home Program, a Financing Partner can purchase the home you're renting, and you live in it as the Future Owner while you work toward qualifying for your own mortgage.
Is Ownable a rent-to-own program?
No. Ownable is an equity-building program. Future Owners build an equity stake scaled to their down payment, and the goal is a conventional mortgage in their own name.
Is mortgage approval guaranteed at the end?
No. Your mortgage will be approved, or not, by a lender on its own merits on the day. Ownable's role is to help you get get into a house and support you as you get mortgage-ready.
Is your landlord selling, or are you tired of waiting for "not yet" to turn into "yes"?
✓ Book a no-obligation call with Ownable to find out where you stand, even if the answer is "not yet, and here's exactly why."
Names and identifying details may have been changed. This case study is for information only and is not mortgage, legal, tax or financial advice. Program terms are set individually. Mortgage approval is never guaranteed and depends on lender criteria at the time. Independent legal advice is required before entering any Ownable agreement.
Ready to see if you qualify? Check out our pre-qualification page to start your journey.
Related Articles
How to Succeed in Rent-to-Own: 5 Things That Decide Whether You Actually Buy the Home
Most rent-to-own families who fail do it on the day they sign. Here are the five things that decide whether you actually buy the home at the end.
Rent-to-Own vs. Mortgage: What's the Difference in Canada?
A mortgage lets you buy a home today. Rent-to-own is a 3 to 5 year bridge to qualifying for one. Here is how they differ on cash, credit and the stress test.
How Does Rent-to-Own Work in Ontario? A Plain-Language Guide
Learn how rent-to-own works in Ontario, step by step: the 5% down payment, monthly payments, term length, red flags, and how you buy the home.