
5 Life Events That Can Derail a Mortgage Without Making You a Bad Buyer
Divorce, a job change, self-employment, newcomer status, and a consumer proposal don't make you a bad buyer, just one who needs more time.
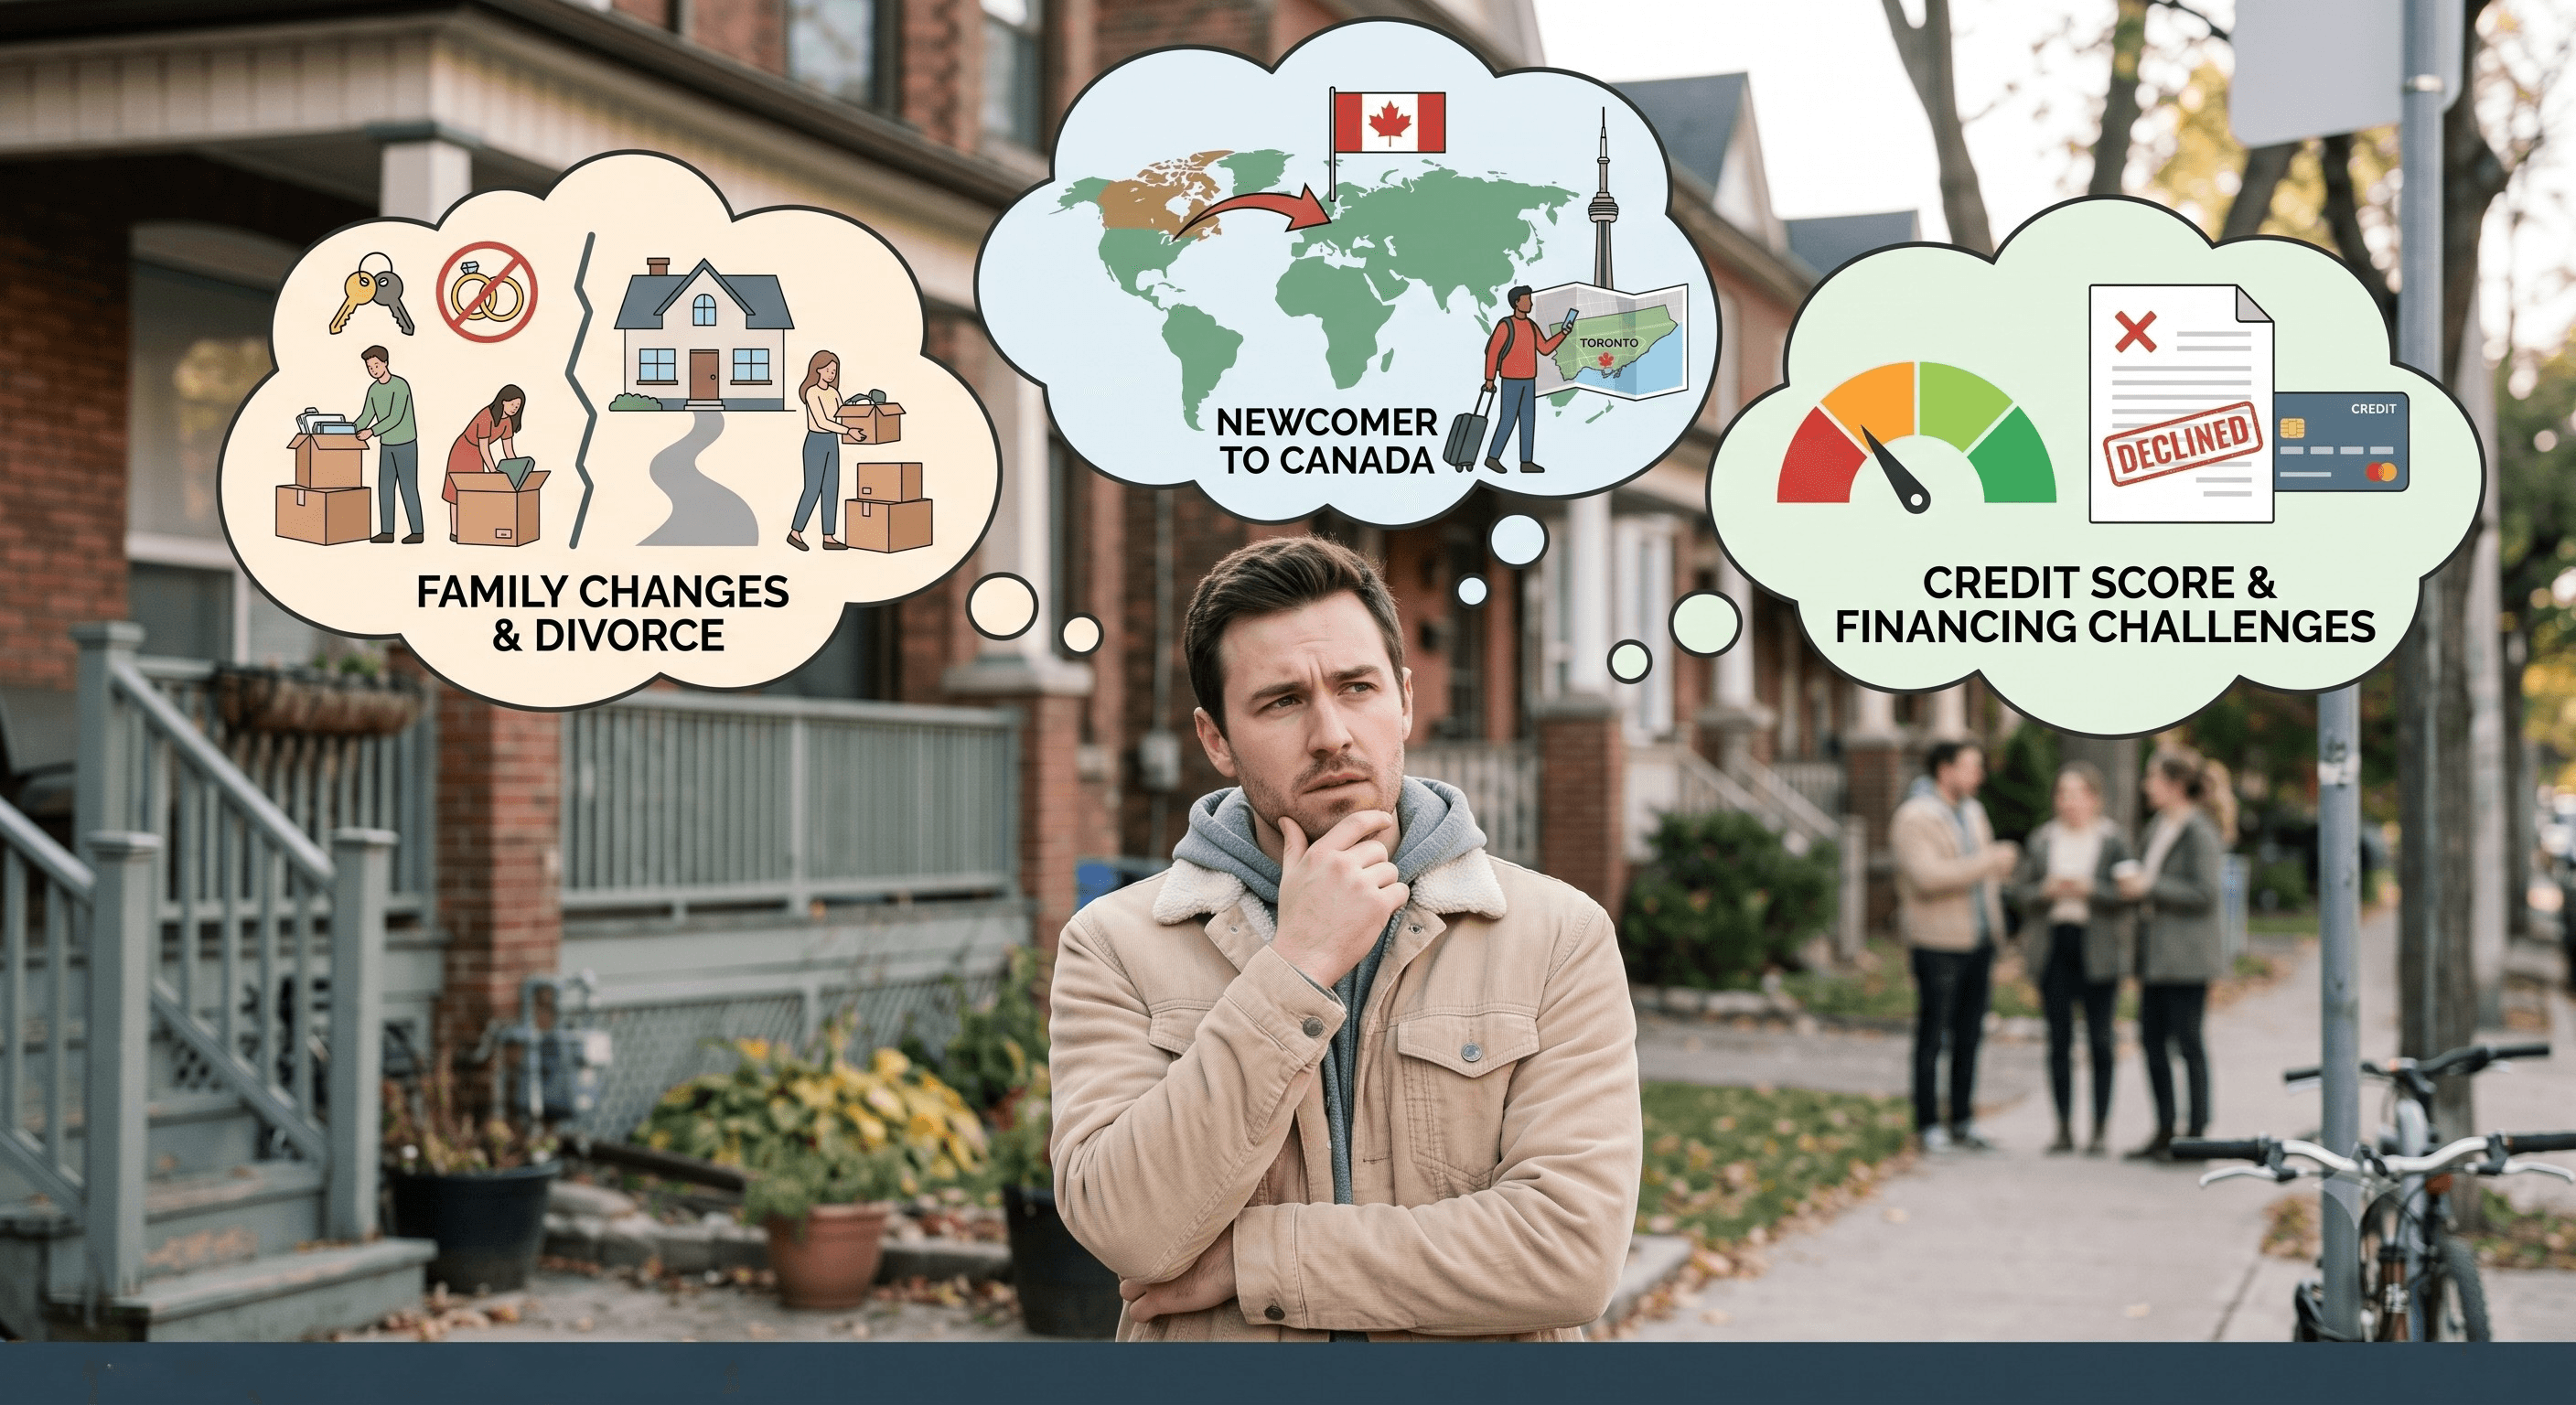
Divorce, a job change, newcomer status, self-employment income, and an active consumer proposal are five of the most common reasons a mortgage lender says no. None of them means you're a financial risk. Each one changes how a lender reads your file today, not who you are as a buyer.
Knowing the difference is the first step toward a realistic timeline back to homeownership.
Why Does Divorce Make It Harder to Qualify for a Mortgage?
Divorce splits one household income into two, often alongside support payments, legal costs, and a credit file that still shows joint debt. Lenders don't see a bad buyer, they see two unsettled income and credit pictures where there used to be one stable one. Rebuilding usually takes 12 to 24 months of independent income and on-time payments in your name alone. That's a timeline, not a life sentence.
Can a Recent Job Change Hurt a Mortgage Application?
Most lenders want two years of continuous income history in the same field, especially if you're in a probation period, switched careers, or moved from contract to permanent work. A better job, in other words, can look worse on paper the week after you take it. The fix is simply time: once new pay stubs and a T4 or two accumulate, the same income that raised a flag becomes proof of stability.
Why Don't Newcomers to Canada Qualify More Easily?
Many newcomer buyers arrive with strong income, savings, and an excellent credit history from home, none of which Canadian lenders can see. Mortgage approval here depends on a Canadian credit file, typically two years deep. It isn't a judgment on newcomer buyers; it's a data gap that closes with time and deliberate credit-building. There is also the question of Permanent Residency and the time if takes for PR to be approved.
Does Self-Employment Income Count Against You With Lenders?
Self-employed Canadians often legally minimize taxable income through write-off, smart tax planning that can shrink the "qualifying income" a lender sees on two years of Notices of Assessment. A business owner with strong cash flow can look, on paper, weaker than an employee earning far less. This is a documentation problem, not a creditworthiness problem.
Can You Buy a Home During or After a Consumer Proposal?
This one deserves a straight answer. An active consumer proposal complicates timing more than anything else on this list. Most lenders want the proposal fully discharged, followed by one to two years of re-established credit. If a proposal is set to close around the same time a rent-to-own term ends, that often isn't enough runway to qualify for a mortgage at the finish line. The honest fix is paying down the proposal faster where possible, to build more discharged, credit-rebuilding time before any purchase deadline arrives.
Where Rent-to-Own Fits In
None of these five situations makes someone a bad buyer, they make someone a buyer who needs time the conventional mortgage timeline doesn't offer. That's the gap a rent-to-own program is built to bridge, not replace. At Clover Properties, homeowners move into a home today under an option agreement, putting down at least 5% of the home's value (never less than $20,000) as a down payment, money they get back toward the purchase when they buy, though it isn't refunded if the homeowner walks away or misses payments. The timeline, terms, and equity sharing split are locked in from day one; the final sale price is not, since there's no price lock and is based on market-value at the time of exit. Homes are held by private investor families, not a corporation, and every agreement should be reviewed with an independent lawyer before signing. The goal from day one is a standard mortgage with an A-lender, rent-to-own is the bridge, never the destination.
To be direct: this isn't the right fit for everyone on this list. Someone a few months from qualifying outright may do better waiting. That's worth an honest conversation before signing anything.
Frequently Asked Questions
Does divorce ruin my chances of getting a mortgage?
No. It resets your qualification timeline — typically 12 to 24 months of independent credit history — but it doesn't disqualify you permanently.
How long after a job change can I qualify for a mortgage?
Most lenders want two years of income history in your new role or field, though some accept less with a strong offer letter and probation completed.
Can newcomers to Canada get a mortgage without Canadian credit history?
Not immediately. Most lenders require roughly two years of Canadian credit history, regardless of income or credit history abroad.
Does being self-employed hurt my mortgage application?
It can affect your qualifying income on paper, even with strong actual cash flow, since lenders average two years of Notices of Assessment after write-offs.
Can I qualify for a mortgage while in a consumer proposal?
Generally not until it's discharged and followed by one to two years of rebuilt credit — so timing your proposal payoff against any purchase deadline matters.
-----
Want to set up a call to discuss your situation further? I would be happy to see where things stand for you and if we can be your "bridge" towards home ownership. Click here to book a call.
Related Articles
How to Succeed in Rent-to-Own: 5 Things That Decide Whether You Actually Buy the Home
Most rent-to-own families who fail do it on the day they sign. Here are the five things that decide whether you actually buy the home at the end.
Rent-to-Own vs. Mortgage: What's the Difference in Canada?
A mortgage lets you buy a home today. Rent-to-own is a 3 to 5 year bridge to qualifying for one. Here is how they differ on cash, credit and the stress test.
How Does Rent-to-Own Work in Ontario? A Plain-Language Guide
Learn how rent-to-own works in Ontario, step by step: the 5% down payment, monthly payments, term length, red flags, and how you buy the home.